Read the inflation and growth print before the desk note hits.
QuantVeritas rebuilds the official inflation and growth data the market watches —
CPI, PCE, and GDP, straight from BLS, BEA, and FRED source files — into
decompositions, robust gauges, and real-time nowcasts published morning-of-release,
with every number traceable to its source series.
One email per release. No spam.
Unsubscribe any time. By subscribing you agree to our
privacy policy.
CPI · PCE · GDP coverage·Median + trimmed-mean robust gauges·Weekly GDP nowcast·OIS repricing
Decomposition
Where the print came from
CPI headline broken into shelter, core services ex-shelter, core goods,
energy, and food — weighted contributions. PCE reported the way a chain
index should be: each cut standalone, no forced partition.
Surprise z-scores
How big the surprise really is
Each subcomponent's surprise scored against its trailing 24-month
distribution — same spec on both gauges. See instantly which line
items are doing the work.
Robust gauges
The center of the basket
Median and 16% trimmed-mean CPI, reconstructed and tracked against the
Cleveland Fed print, plus the breadth read — the share of components
rising faster than 3% a year.
CPI ↔ PCE wedge
The gauge the Fed targets
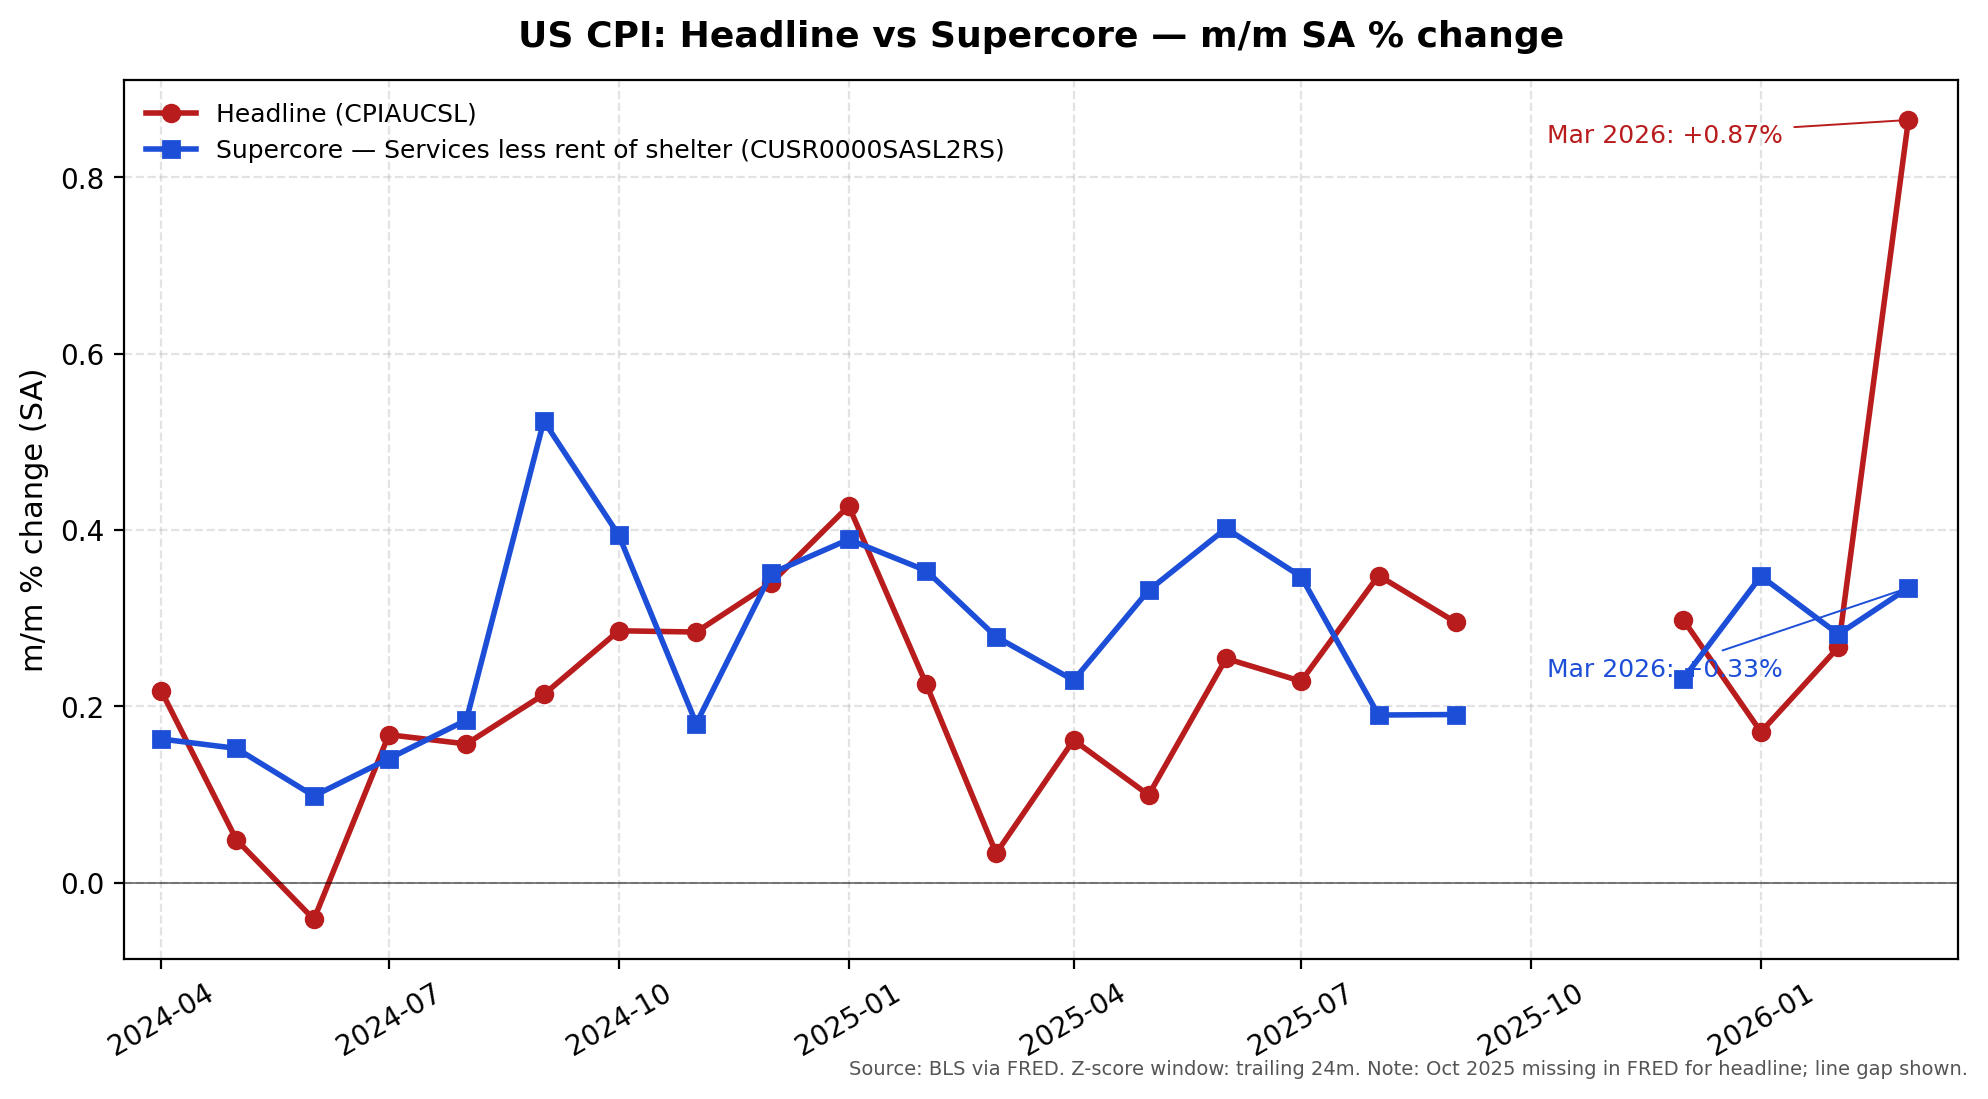
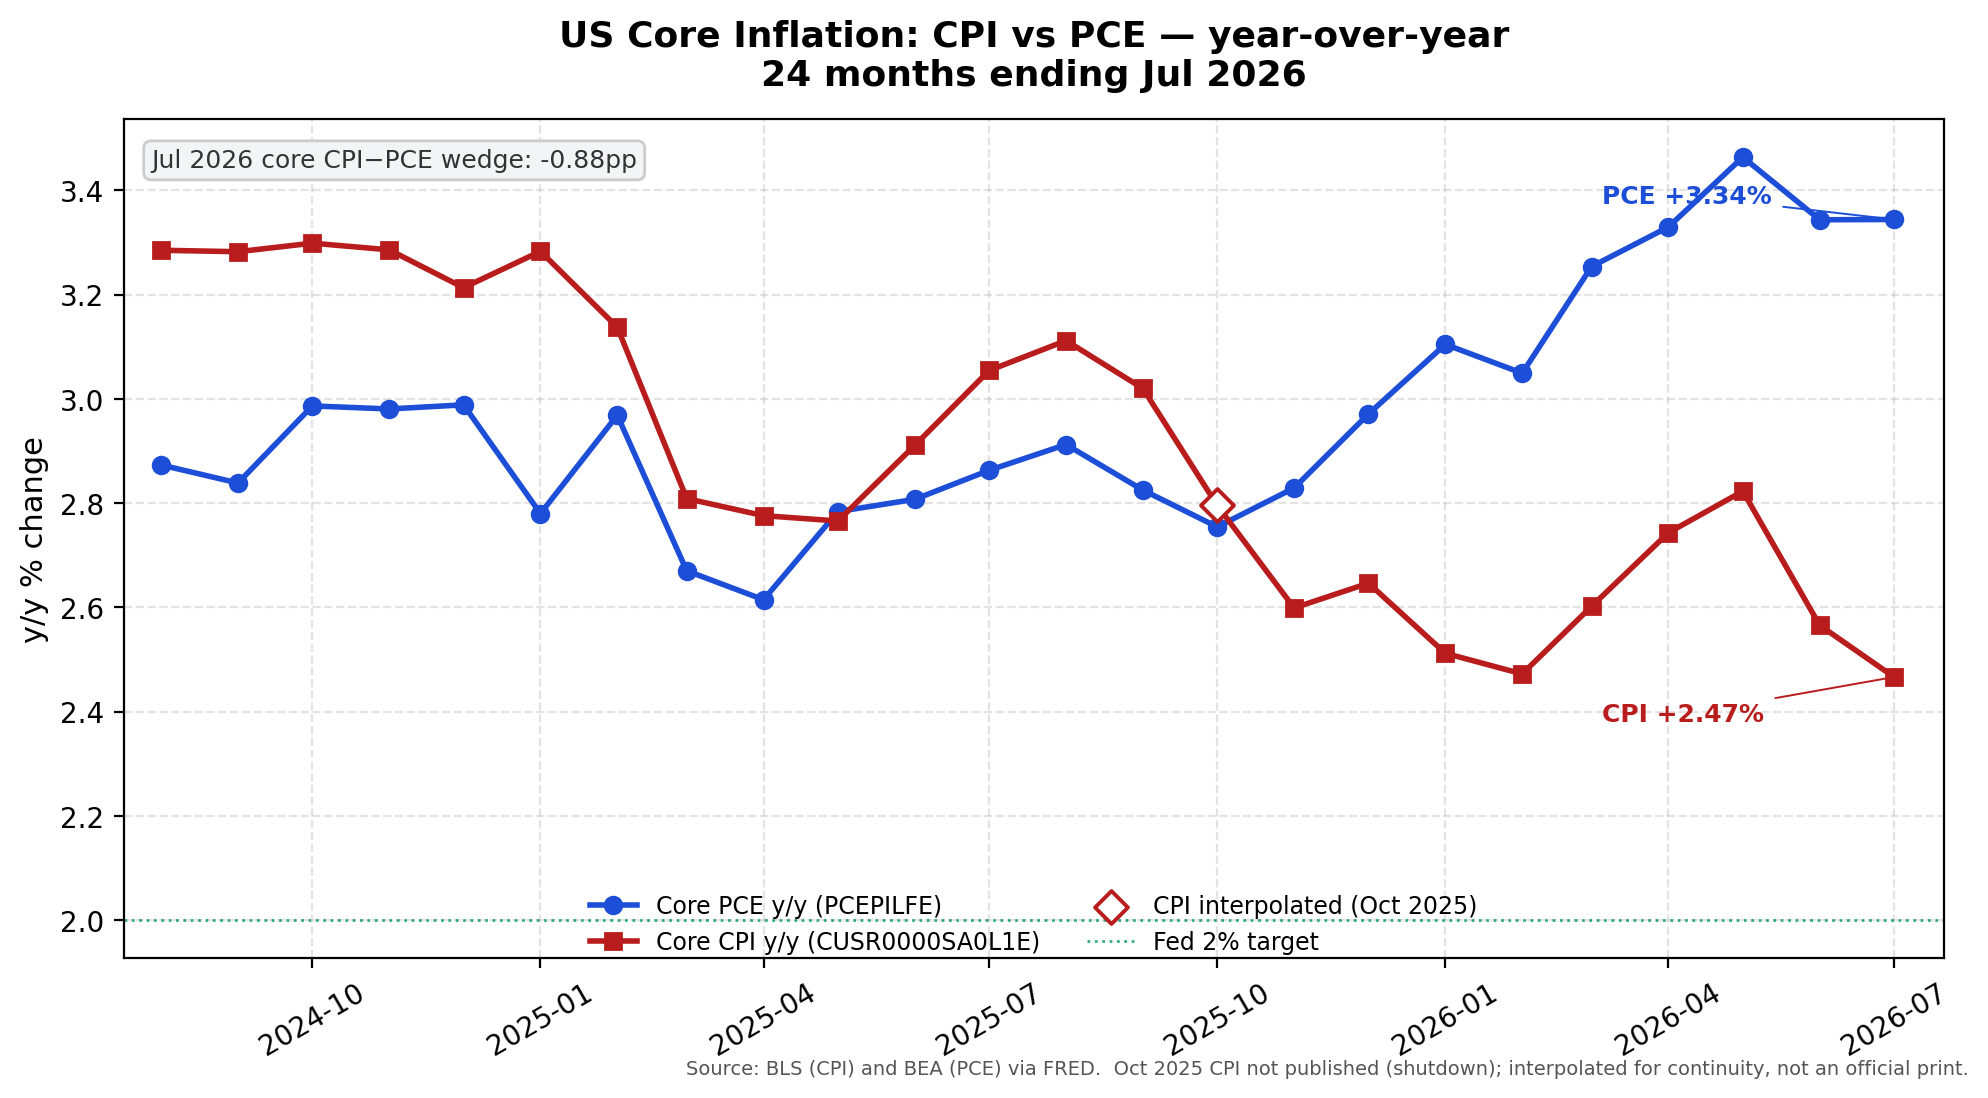
Core CPI and Core PCE side by side, plus supercore (services ex
housing). The monthly agreement and the y/y wedge — the difference
the FOMC actually reacts to — reconciled every release.
Real-time nowcasts
The read before the release
A weekly, vintage-controlled GDP nowcast scored against Atlanta Fed
GDPNow, the NY Fed and the SPF — and high-frequency indicators
signaling component pressure between CPI releases.
Curve repricing
How rates moved on it
OIS curve at 8:29 vs. 8:35 ET on the CPI print. Repricing in basis
points through year-end, with an EFFR-SOFR basis cross-check that
separates Fed-path repricing from money-market plumbing.
What you'll see in your inbox.
The decompositions, robust gauges, and gauge wedge behind every release — with the GDP nowcast tracking in between.
CPI: Headline vs Supercore (services less rent of shelter), m/m SA.
Source: BLS Public Data API v2 (CUSR0000SA0, CUSR0000SASL2RS).
Core inflation: CPI vs PCE, y/y — the gauge wedge.
Source: BLS (CUSR0000SA0L1E) and BEA (PCEPILFE) via FRED.
See what subscribers get.
The full Macro Intelligence memo from the March 2026 CPI release —
component decomposition, surprise z-scores, OIS reaction window,
sector mapping, and conditional positioning bias. Every CPI release now
ships with a matched PCE companion — Core PCE, supercore, and the gauge wedge.
The weekly GDP nowcast ships its own read, scored against GDPNow, the NY Fed, and the SPF.
Reproduced unedited.
Launch pricing: premium is $29/month or $290/year (about two months free) for the waitlist cohort — locked in for as long as you stay subscribed. The standard rate rises to $49/month / $490/year after launch. One email per release; cancel any time.
Who's behind QuantVeritas.
I'm Terence Agbeyegbe, Professor of Economics at
Hunter
College, CUNY.
Applied econometrician with 20+ years researching the methods most desks
use to read inflation. QuantVeritas is the tool I always wished I had on
release morning.
I'm joined by Toneukarin Agbeyegbe,
Quantitative Analyst, who holds an MS in Statistics from Rutgers University
and works on the release analytics and report production.